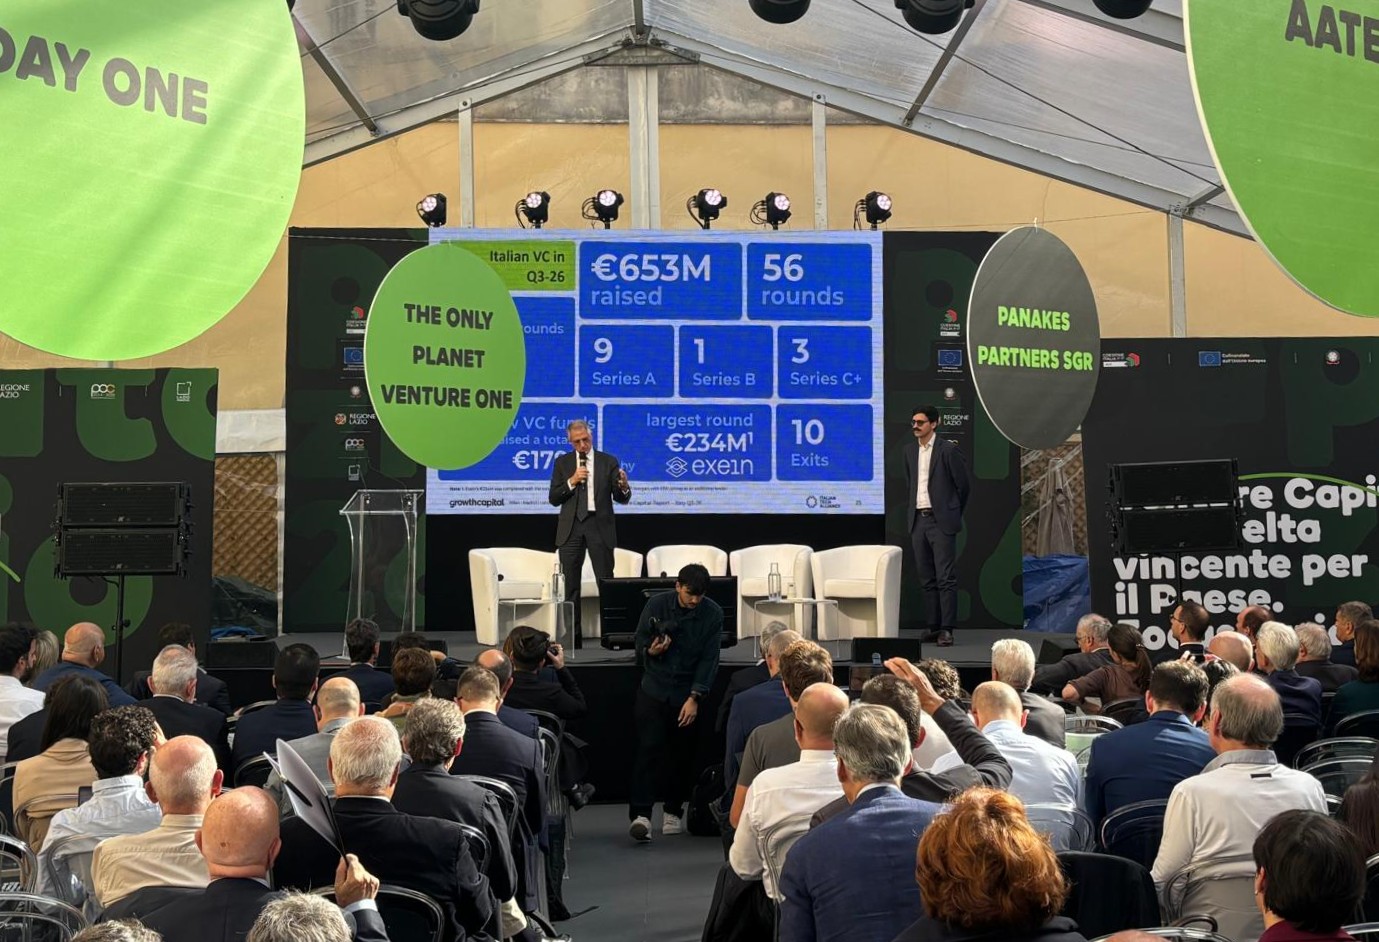
Growth Capital, in collaboration with Italian Tech Alliance, presents the Venture Capital Report for Italy covering Q3-26 and the first nine months of 2026. Presented in Rome on October 22nd, the report outlines the main developments in the Italian venture capital ecosystem, with a focus on investment activity, round sizes, sector trends and fundraising, alongside a deep dive on CleanTech developed with CDP Venture Capital.
“In Europe, the number of rounds is in line with 2025, while the capital invested in nine months is already comparable to the whole of last year, driven mainly by AI. As we predicted in previous years, the Italian market is maturing: rounds are falling, but the amount raised has risen to €1.465 billion, driven by three mega rounds worth a combined €442 million, and we expect it to surpass 2025.” comments Fabio Mondini de Focatiis, Founding Partner of Growth Capital.
2026 YTD: More Capital, Fewer Rounds
In the first nine months of 2026, investments in Italian startups and innovative companies reached €1,477 million across 210 rounds, compared with €855 million across 307 rounds in the same period of 2025. Capital invested has already exceeded the 2024 total, while the number of rounds fell by 31%. Mean and median round sizes reached record highs of €7.0 million and €2.0 million respectively, a clear sign of a maturing market.
Q3-26 brought €653 million across 56 rounds, the second-best quarter ever for amount invested, driven by €354 million in mega rounds. At the same time, it was the weakest quarter on record by number of rounds, in line with the trend seen across Europe. The largest round of the quarter was Exein’s €234 million Series D.
Market Structure: Series B+ Takes the Lead
The decline in deal count was concentrated in the early stages. Pre-Seed and Seed rounds fell by 42% compared with 2025 YTD (116 vs 201), although they still represented the majority of rounds in Q3-26 (54%). Later stages moved in the opposite direction. Series B+ rounds almost doubled (18 vs 10), raising €660 million and already exceeding full-year 2025. They now account for 45% of total capital invested, as Series A cohorts from recent years progress into later-stage rounds. After a record-low Q2, Series A also rebounded in Q3-26 with 9 rounds and €101 million.
Sector Trends: Software and AI Keep the Lead
Software confirmed its position as the leading sector in 2026 YTD, with 52 rounds (one in four of the total, 77% of them AI-related) and €512 million raised, equal to 35% of capital invested. Life Sciences (€258 million), Smart City (€209 million) and FinTech (€195 million) followed, with the top four sectors together accounting for 80% of capital. In Q3-26, investment was especially concentrated: Software (€296 million) and Life Sciences (€199 million) absorbed three quarters of the total.
Exits and Fundraising
Italy recorded 25 exits in 2026 YTD (10 of them in Q3-26), including 23 M&A transactions and two IPOs on Nasdaq: Bending Spoons and Newcleo. On the fundraising side, Q3-26 was the strongest quarter of the past year, with 8 new funds raising €179 million, more than Q1 and Q2 combined. In total, 11 new Italian VC funds raised €283 million in 2026 YTD, already more funds than in all of 2025, though with a smaller average size (€26 million).
A Deep Dive on CleanTech
This edition includes a dedicated focus on CleanTech, developed with CDP Venture Capital. CleanTech behaves as a distinct venture asset class: hardware-intensive, sensitive to policy, increasingly driven by energy security, and ultimately won on unit economics. In Italy, the sector has attracted €1.6 billion since 2021, and deal flow has roughly doubled (from 37 rounds in 2021 to 71 in 2025). Yet CleanTech accounts for only 13% of Italian VC in 2026 YTD, compared with around 25% in Europe. CDP has mobilised €245 million in the sector, through direct investments in 97 companies and fund investments reaching 27 more. The report highlights a broader shift: as AI makes software easier to build, value moves to what is hard to replicate, such as hardware, manufacturing know-how and physical assets.
The European Context: Mega Rounds and Defence Tech
At the European level, 2026 YTD recorded €68 billion invested across 7,312 rounds, nearly matching full-year 2025, with mega rounds accounting for their largest share ever. Q3-26 was the best quarter for amount invested since Q2-22, and deal count is expected to grow year on year for the first time in six years. DefenseTech attracted €6.3 billion, nearly three times its 2025 total. The gap with the US, however, keeps widening: US VC reached €444 billion in 2026 YTD, 6.5 times Europe’s, driven largely by AI mega rounds.
Outlook
The Italian ecosystem shows a broad and healthy base, with €1 billion raised in rounds under €100 million. Exein’s Series D and Bending Spoons’ IPO have put global investors’ eyes on Italy, and 2026 is set to exceed 2025, provided at least one more mega round closes in Q4. The main challenge remains the early stage, where fewer rounds point to continued investor selectivity. In Europe, tech sovereignty is emerging as a new engine for VC, and applied AI, rather than foundation models, is where the continent can compete.
Link to the full report here